
Instant Cash Advance: CashHoop
- Rating
- 4.6
- Downloads
- 1.00M
- Content Rating
- Everyone
Instant Cash Advance: CashHoop - Screenshots
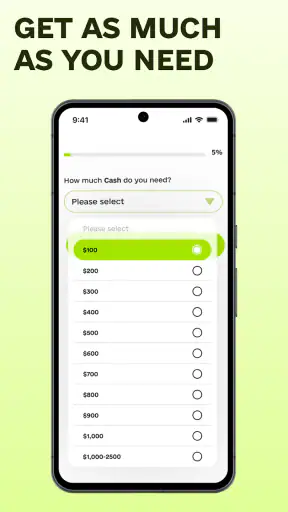
Pros
- Quick application process with minimal paperwork required.
- Clear repayment terms are shown before accepting an advance.
- Useful for covering unexpected short-term expenses.
- Simple interface makes account navigation easy.
- May offer flexible advance amounts based on eligibility.
Cons
- Approval and advance amounts depend on your personal eligibility.
- Fees may make borrowing expensive for frequent users.
- Repayment is typically required within a short period.
- Availability and terms can vary by state or region.
- Late repayment could lead to additional charges or account restrictions.
Instant Cash Advance: CashHoop - Description
- App Name
- Instant Cash Advance: CashHoop
- Package Name
- com.loans.instant.cash.advance.app
- Developer
- Biskup Apps
- Category
- Finance
- Last Updated
- Jul 17, 2024
- Version
- 1.0.15
CashHoop caught my attention because it approaches a very specific money problem: getting through a short gap between an expense and the cash available to cover it. I reviewed it as a finance app from Biskup Apps, and my first impression was that its value depends less on how exciting it feels and more on whether it helps without creating a new problem later. That is the right standard for any cash-advance service.
The app is free to install, aimed at an Everyone audience, and available on devices running Android 7.0 or later. Its store presence is already substantial, with more than a million installs, a 4.6 average from roughly 26 thousand ratings, and about 1.4 thousand written reviews. Those figures suggest that many people are at least willing to try it, but they do not remove the need to read each offer carefully before accepting anything.
What using CashHoop feels like at first
The first-week appeal is easy to understand. When an unexpected bill arrives, the usual alternatives can be slow, inconvenient, or poorly matched to a small and urgent need. CashHoop presents itself as a way to request a cash advance quickly, while also bringing tax filing into the same general money-management space. That combination makes it more relevant to someone dealing with several immediate financial tasks rather than someone simply browsing for a budgeting tool.
I would approach the initial setup with a clear purpose instead of opening the app casually. Decide whether the need is a genuine short-term bridge, a tax-related task, or both. Having that answer ready makes it easier to judge what the app is asking for and whether the result is useful. A cash advance should solve a defined timing problem, not become a routine substitute for income.
The most important early habit is to separate the application process from the borrowing decision. Reaching an eligibility screen or seeing an available option does not automatically make that option affordable. Before proceeding, I would check the repayment amount, timing, any applicable charges, and the effect on the next pay cycle. Fast access is only helpful when the repayment plan is equally clear.
That is where CashHoop needs a more careful reading than a normal free finance app. “Free” describes the download, not necessarily every financial service connected with it. I would never treat the absence of an upfront app price as proof that an advance has no cost. The practical question is the total amount that leaves my account and when it leaves.
For a realistic example, imagine that a utility payment is due before payday and a late fee would be painful. I might use the app to explore whether an advance can cover that narrow gap, then compare the complete repayment obligation with the late fee and with alternatives such as asking the provider for an extension. If the advance would leave too little money for food, transport, or another fixed bill, I would not take it merely because the request is convenient.
The tax angle also deserves a deliberate approach. Combining tax filing with emergency cash access may be useful during a busy financial period, but those are different decisions. Filing accurately requires time to check income records, deductions, and personal details. I would not rush through a tax workflow because I was focused on receiving money, and I would not borrow simply because the two options appear next to each other.
Where it fits beside familiar alternatives
CashHoop is not a replacement for a conventional bank account, a full budgeting app, or a long-term savings plan. A bank may be better for predictable access to established funds, while a budgeting tool is better for tracking spending over several months. An employer-based early-pay option may also suit someone whose workplace already offers one, especially if its repayment terms are easier to understand.
Compared with asking family or a bill provider for flexibility, a cash-advance app can feel more private and immediate. The trade-off is that a personal arrangement may be cheaper, while a provider extension may avoid borrowing altogether. I see CashHoop as a tool for comparing options during a tight moment, not as the automatic first choice for every shortfall.
One useful first-week technique is to write down the exact reason for opening the app and the exact date the gap should end. If the need has no clear endpoint, the product is being asked to solve a recurring income problem, and that is a warning sign. This small check prevents the convenience of the interface from disguising a larger financial issue.
Whether the value survives beyond the emergency
Month-to-month value is harder to judge than first-use appeal. A cash advance is naturally occasional; it does not create lasting value simply because it was helpful once. For me, the app earns a continuing place only if it supports better decisions around taxes, upcoming bills, and short-term cash flow without encouraging repeated borrowing.
The tax-filing function could give the app a more durable role for people who need that service during the year. Even then, I would keep the tax workflow separate from emergency borrowing in my own routine. First complete the tax-related work carefully, save or record the relevant outcome, and only then consider whether a cash advance is necessary. Treating the two as separate checkpoints reduces the chance of making a rushed decision.
Another practical use is preparing before a predictable pressure point. If a yearly bill, school expense, or seasonal cost tends to arrive at the same time, I would use the app as one comparison point well before the deadline rather than waiting until the last hour. That gives me time to check savings, payment arrangements, and other sources of funds. The app is more useful as part of a decision process than as a panic button.
There is also a subtle trade-off between convenience and financial visibility. If an app makes it very easy to request money, I may feel less pressure to examine why the shortfall happened. I would therefore keep a simple note after every use: what the money covered, when repayment is due, and what change could prevent the same gap next time. The note takes little effort, but it turns a one-off advance into information about my cash flow.
For someone with irregular income, that reflection may be especially important. A single advance can smooth timing, but repeated advances can make the following month tighter. In that situation, a stable budgeting system, a conversation with creditors, or professional financial advice may be more valuable than another quick request. CashHoop should not be treated as evidence that a recurring deficit has been fixed.
The app’s current version is 1.0.15, and its release date was July 17, 2024. I would keep an eye on updates before relying on it for an important deadline, particularly when using the tax side of the service. Updating is not exciting maintenance, but financial applications are the wrong place to postpone routine software upkeep.
The maintenance that determines whether it stays installed
CashHoop is not the kind of app I would open every day just to browse. Its maintenance burden is mostly financial rather than technical: reviewing repayment dates, checking account balances, keeping tax information organized, and removing the app if it no longer serves a clear purpose. That is manageable, but it requires discipline.
I would also avoid leaving an advance decision until the moment a payment is due. A last-minute workflow encourages accepting the first available option instead of comparing the total cost and timing. Even if the app is quick, my own review should not be rushed. I would read the final confirmation screen slowly and save the repayment details somewhere I can find them.
Privacy and account security deserve the same attention as the financial terms. I would use a strong device lock, avoid handling sensitive tax or banking information on a shared device, and review every screen before submitting personal details. These are sensible precautions for any finance app, but they matter more when one product touches both tax work and access to money.
If I stopped using the service, I would first confirm that any outstanding obligation was settled and that I had retained the records I needed. Only after that would I remove it from my phone. Deleting an app is not the same as closing a financial relationship, so the cleanup should follow the account status and documentation rather than happen impulsively.
The app’s Everyone rating may make it look broadly approachable, but age suitability is not the same as financial suitability. A young or inexperienced user may still need help understanding repayment, fees, and the consequences of missed timing. I would want a trusted adult or financially knowledgeable person involved if the terms were difficult to interpret.
What could create fatigue over time
The biggest source of fatigue is the gap between a smooth request process and the less pleasant repayment that follows. A quick advance can feel like immediate relief, while the cost becomes noticeable only when the next income arrives. That emotional timing can encourage repeat use, especially if the original expense was not unusual but part of a continuing pattern.
Another point of friction is comparison. A cash-advance offer is not automatically better than a bank overdraft, a credit-union product, an employer option, a payment extension, or simply delaying a nonessential purchase. I would compare the full repayment amount and consequences, not just the amount that appears available. If the app does not make that comparison easy, I would do it manually before agreeing.
Tax filing can introduce a different kind of tiredness: detail overload. People often open a finance app when they are already stressed, and a tax task may require documents they do not have nearby. My advice is to gather records first and use a quiet session for filing. If an answer is uncertain, stopping to verify it is better than completing the process quickly with an avoidable mistake.
I would also resist turning notifications or reminders into background noise. A finance app earns attention when it helps me act on a specific deadline; it loses value when I stop reading because every alert feels urgent. Keeping only useful reminders, where the controls allow it, would make the app easier to live with. If the experience begins to feel like pressure rather than assistance, that is a reason to reassess the service.
For people who already have a reliable emergency fund, CashHoop may offer little month-to-month benefit. Using saved money can be simpler and less expensive than taking an advance, provided the withdrawal does not undermine a more important reserve. Likewise, someone seeking detailed spending categories, investment tools, or long-term financial planning would be better served by a dedicated product built for those jobs.
I would skip CashHoop if I could not state exactly how repayment would fit into my next budget. I would also skip it if I needed a large, long-term loan, if the expense was discretionary, or if I was already using advances to cover earlier advances. Those situations call for a different solution, not a faster version of the same cycle.
My long-term verdict
CashHoop earns lasting space only when it remains a controlled backup, not a monthly habit. Its strongest case is a clearly defined short-term cash gap combined with a need to handle tax filing in the same financial season. The free app, broad device compatibility, and strong user response make it easy to try, but ease of access should never replace careful reading of the actual offer.
After the novelty fades, I would keep it installed only if I had a specific reason to return: a legitimate tax task, a need to compare a short-term option, or a repayment record still being managed. I would not keep opening it out of habit or use it as part of my normal monthly spending plan. That distinction is what separates a useful safety net from a recurring source of pressure.
My final recommendation is cautious but positive for the right user. If you understand the repayment obligation, have a realistic plan for the next income date, and compare the advance with less expensive alternatives, CashHoop can be a practical option to investigate. If you need ongoing help balancing your budget or escaping repeated shortfalls, I would choose a broader financial strategy instead and treat this app as, at most, a temporary supporting tool.
FAQ
What is Instant Cash Advance: CashHoop, and how does it work?
Instant Cash Advance: CashHoop is a financial app designed to help eligible users explore short-term cash advance options through a mobile application. After creating an account, you may be asked to provide personal, employment, income, and banking information so the service can assess your request. CashHoop may connect users with third-party lenders or financial providers, so approval, loan terms, fees, and funding times can vary.
Can everyone qualify for a cash advance through CashHoop?
No. Access to a cash advance is not guaranteed for every applicant. Eligibility may depend on factors such as age, location, income, employment status, an active bank account, and the information submitted during registration. Some requests may be declined, while others may receive different offers or limits. Before accepting anything, review the displayed requirements and make sure the repayment terms fit your budget.
How much does using CashHoop cost?
The cost depends on the offer presented to you and the provider ultimately handling your request. Potential charges may include service fees, lender fees, express-funding fees, interest, or other costs. The app itself may also have separate terms from those of a lender. Carefully read the final agreement, including the annual percentage rate, total repayment amount, due date, and any late-payment consequences before accepting an offer.
When will I receive money after requesting an advance?
Funding time is not necessarily instant, despite the wording commonly used in cash advance advertising. If your request is approved, the provider may send money to your verified bank account, but delivery can depend on bank processing, identity verification, operating hours, weekends, and whether you choose an expedited option. Always check the estimated arrival time and any additional fee before confirming the transaction.
Is CashHoop safe to use, and what information does it require?
CashHoop may request sensitive details such as your name, contact information, date of birth, employment and income data, identity information, and bank-account details. Before using it, review the app’s privacy policy, permissions, security practices, and the identity of any third-party provider involved. Download only from an official store, avoid sharing login codes, and never accept an offer without understanding how your information and repayment obligations will be handled.


